
Debt Consolidation Strategies: Achieving Financial Freedom


Understanding Debt Consolidation
Debt consolidation is a financial strategy aimed at simplifying and reducing your debt load. By combining multiple debts into a single loan, you can streamline your payments and potentially secure a lower interest rate. This approach can be a lifeline for those struggling to manage multiple debts.
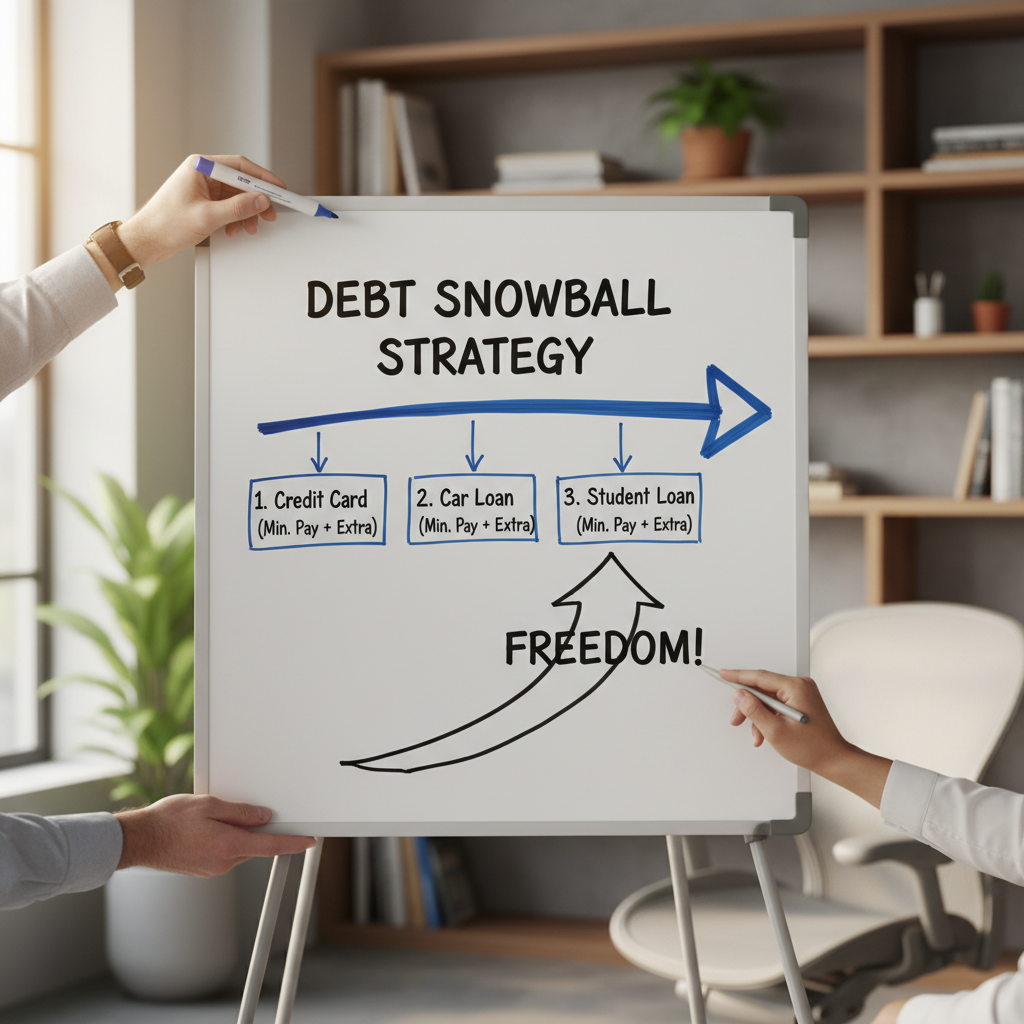
It's important to understand that debt consolidation doesn't erase your debt. Instead, it restructures it into a more manageable form. This strategy is particularly useful for credit card debts, personal loans, and other high-interest obligations.
Types of Debt Consolidation
Balance Transfer Credit Cards
One popular method is using balance transfer credit cards. These cards offer a low or 0% introductory interest rate, allowing you to transfer existing credit card balances to a new card. This can save you money on interest if you pay off the balance within the promotional period.
Personal Loans
Personal loans can be used to consolidate debts with fixed monthly payments and interest rates. This option provides predictability in your payments and can often be obtained through banks or online lenders. It's crucial to compare interest rates and terms to find the best deal.
Benefits of Debt Consolidation
Debt consolidation can offer several benefits, including streamlined payments, potentially lower interest rates, and improved credit scores over time. By focusing on a single debt, you can reduce the risk of missing payments and incurring penalties.
Moreover, consolidating debt can enhance your financial planning and budgeting efforts. With a clearer view of your financial obligations, you can strategize more effectively to achieve long-term financial freedom.
Considerations Before Consolidating
Before deciding on debt consolidation, assess your financial situation carefully. Consider the total cost of the new loan, including any fees, and ensure that it aligns with your financial goals. It’s also crucial to understand the terms and conditions associated with your new loan.
Impact on Credit Score
While debt consolidation can improve your credit score over time, the initial inquiry and new account may temporarily affect it. However, consistent, on-time payments can help rebuild and strengthen your credit profile.
Steps to Successful Debt Consolidation
- Evaluate all existing debts and interest rates.
- Research and compare consolidation options.
- Create a realistic repayment plan.
- Monitor your progress and adjust as necessary.
By following these steps, you can work towards financial stability and ultimately, financial freedom.